
This policy brief provides a series of data snapshots that illustrate our state’s progress toward embedding the values of fairness, care, and opportunity into the foundations of our economy. EOI’s goal is not just to track the state of opportunity in Washington, but over the long run, to change it – to make those values real for everyone who calls this place home.
Good Jobs
Most full-time jobs in Washington – and across the nation – do not pay enough for people to make ends meet. Despite their hard work, everyday Washingtonians are overwhelmed by low wages and a high cost of living.
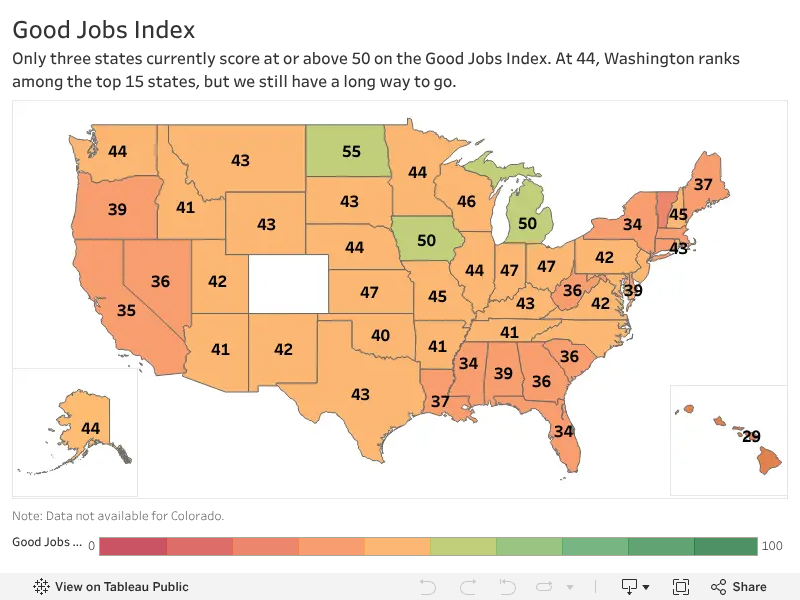
EOI’s Good Jobs Index (GJI) helps us better understand how well our economy does at providing jobs that pay enough to support people.[1] A score of 100 on the GJI would mean every job in a given state’s metropolitan area(s) pays enough for various households (ranging from one person living alone to two adults and two children living together) to have a reasonable standard of living.
While Washington ranks among the top 15 states on the GJI overall, a score of 44 is still a failing grade – we have a long way to go before our state is a place where most full-time work can support a household.
Overall, just 36% of occupations at the 25th wage percentile, 46% of occupations at the median wage, and 56% of occupations at the 75th wage percentile pay enough to meet basic budgets for most Washington households.
Wages for occupations in some smaller metropolitan areas, and those in the eastern half of the state, are slightly better – but not by much. Spokane-Spokane Valley and Kennewick-Richland each have a higher Good Jobs index (53 and 52, respectively) than the state overall, while Bellingham (43), Mt. Vernon-Anacortes (43), and Seattle-Tacoma-Bellevue (42) are lower overall.

Wage Equity
If, across all economic sectors (and the occupations within those sectors), wages for people of all races/ethnicities were equitably distributed, we would not see a racial wage gap – and the same is true for gender. Likewise, if economic gains were shared equitably across class lines, the gap between high- and low-income earners would hold steady.
Washington is a prosperous state – but our economic gains are not being shared equitably among those who contribute to them. A review of typical wages across the state’s economy shows deep divides along racial, gender, and class lines – and those gaps are growing.[2]
Sectoral wage data from the U.S. Census shows that since 2014, the racial wage gap has decreased by $1,000 or more in 17 states; by the same measure, the gender wage gap has decreased in 28 states, and the class wage gap has decreased in seven states. But the opposite is true in Washington.
Over the same period, Washington’s overall racial wage gap (across all economic sectors) has grown by more than $47,000, and the class wage gap has grown by more than $14,000 – far more than any other state. The state’s gender wage gap has also grown by more than $3,660 – the third largest increase among all states.

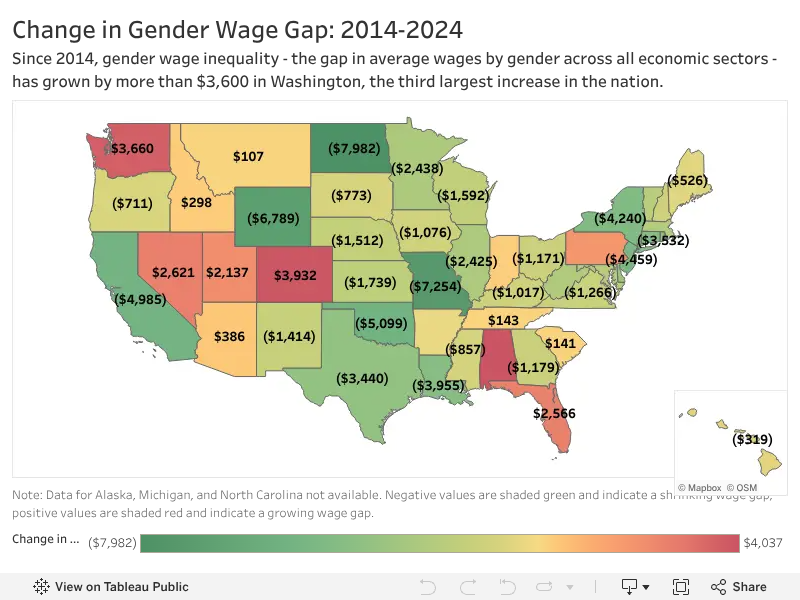

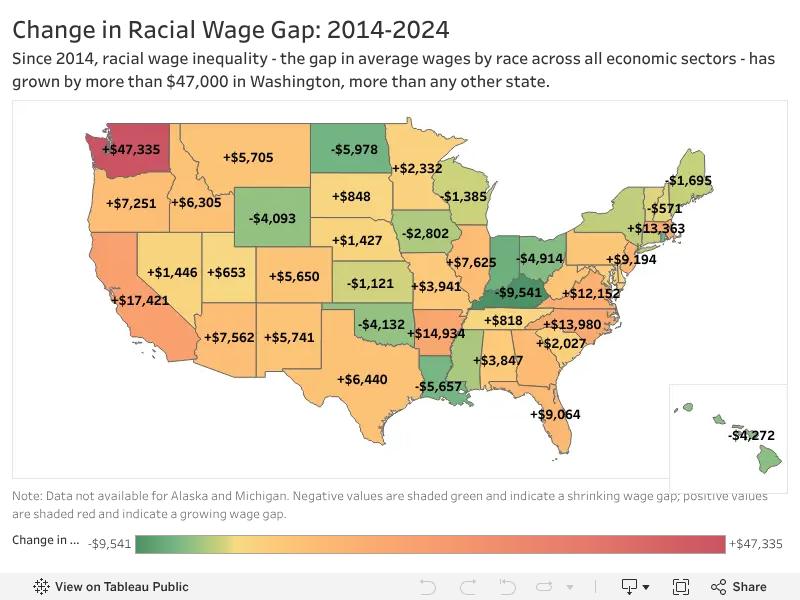

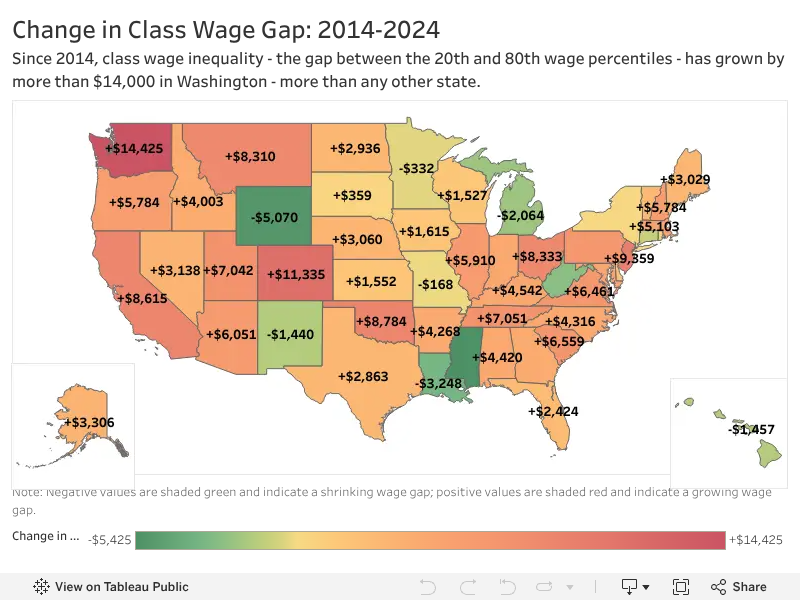
These trends are driven largely by employment growth in the technology sector (and to a lesser extent in professional, scientific, and technical services) – where many jobs pay well above those in other sectors, and the workforce is drawn from across the globe (particularly Asia).
Among Washington’s ten largest employment sectors, which comprise 81% of all jobs:
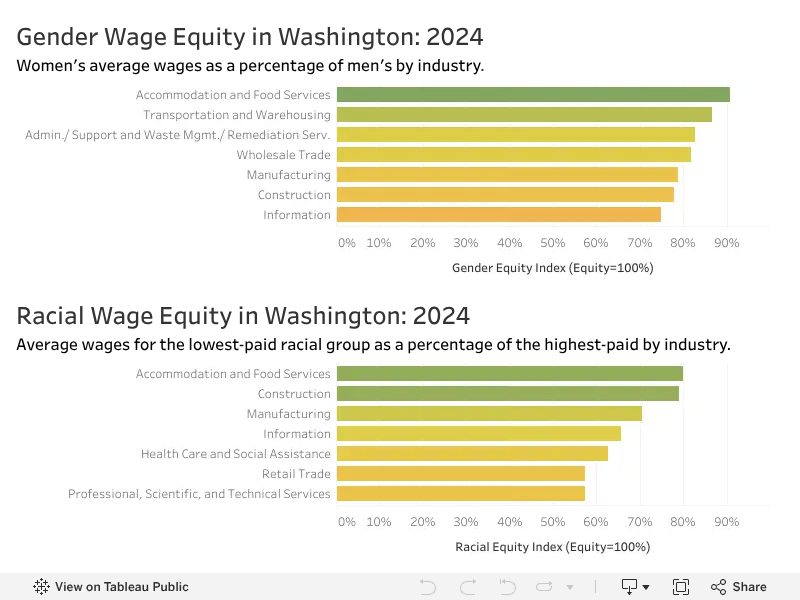
- People are more likely to be paid equitably (regardless of race) in the Construction and Accommodation/Food Services sectors, where the lowest-paid racial groups ( are paid 80% and 79%, respectively, that of the highest-paid (Asian). The Administration/Support and Transportation/Warehousing sectors have the largest racial wage gaps: the lowest-paid racial group in both sectors (Black or African American) earns just 50% and 36%, respectively, of that of the highest-paid (Asian).
- The gender equity wage gap is smallest in the Accommodation/Food Services and Transportation/Warehousing sectors – there, women’s wages are 91% and 79%, respectively, of that of men. The Health Care/Social Assistance sector and the Professional, Scientific, and Technical Services sector have the largest gender equity wage gap: women overall earn 72% and 68%, respectively, of that of men.
The gender wage disparity in Health Care and Social Assistance is particularly egregious, as women outnumber men by more than 3-to-1 in this sector.

Tax Equity
Washington’s tax code has long been one of the most inequitable in the nation – a place where low-income households pay a far higher share of their income in state and local taxes than do their high-income counterparts – but there have been some recent improvements.
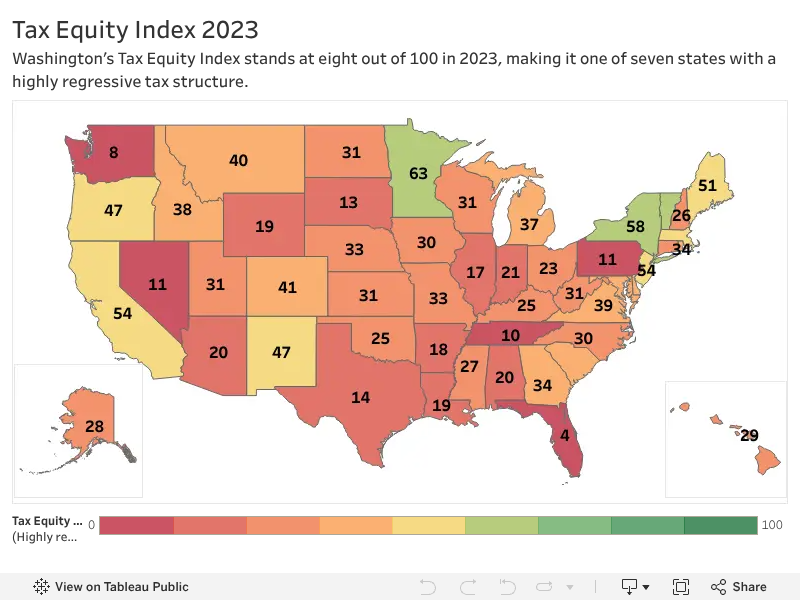
Using data provided by the Institute for Taxation and Economic Policy, EOI’s Tax Equity Index (TEI) offers insight into just how fair (or unfair) each state’s tax code, depending on household income.[3]
A low score indicates a less equitable, or regressive, system where lower-income households pay a higher percentage of their income in taxes. A higher score indicates a more equitable, or progressive, system where higher-income households pay a larger share of their income in taxes.[4]
Nationally, between 2014 and 2023, 34 states improved their tax progressivity to at least some degree. While Washington is one of them, thanks to the state’s Capital Gains Tax and Working Families Tax Credit, the state has much more work to do to create an equitable tax code.
It’s also important to recognize that even where some states’ tax structures are fairer than others, they are still quite moderate. No state can yet boast of having a progressive tax system. While Minnesota, Vermont, and New York have the highest TEI scores (63, 62, and 58 respectively), they are only somewhat progressive. California, New Jersey, Maine, Massachusetts, New Mexico, and Oregon have a neutral tax structure – and every other state is regressive to at least some degree.

Health Care
The cost of health care is pushing many people to an economic breaking point, as out-of-pocket costs (for premiums, deductibles, coinsurance, and co-payments) continue to climb. Likewise, business owners are finding it harder to afford employer-sponsored health plans, and state budgets are being overstretched by increasing health care related costs.
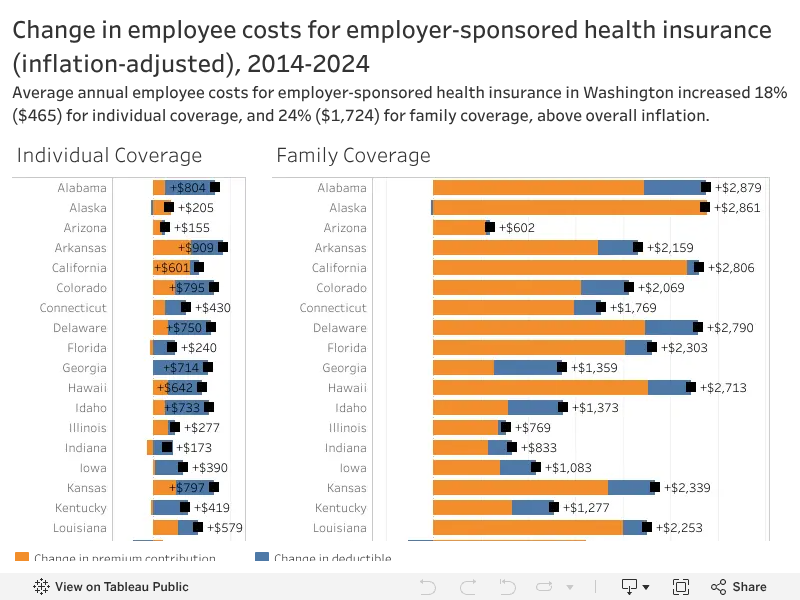
From 2014 to 2024, average annual employee costs (premium contributions and deductibles) for employer-sponsored health insurance in Washington increased 18% ($465) for individual coverage, and 24% ($1,724) for family coverage, above overall inflation.[5] A growing share of workers are also having to enroll in high-deductible health care plans (those with a general annual deductible of $1,000 or more): from just 4% nationwide in 2006 to 30% in 2023.[6] Increases in coinsurance and co-payments are pushing out-of-pocket costs even higher.
Hundreds of thousands of workers and families in Washington – and millions more across the nation – who purchase individual plans on a state or federal health exchange will also face a crisis next year, due to federal funding cuts included in H.R. 1 and other federal policy changes. Due to those cuts, insurers providing plans on Washington’s health insurance exchange are scheduled to increase their rates by an average of 21% in 2026. [7]
For those purchasing health coverage on Washington’s exchange, the loss of federal premium tax credits means payments will more than likely double on average – with an estimated 80,000 Washingtonians likely to forgo health insurance coverage as a result. [8] [9] In addition, an estimated 488 low-income Washington residents are likely to lose federal Medicaid coverage. [10]

Child Care
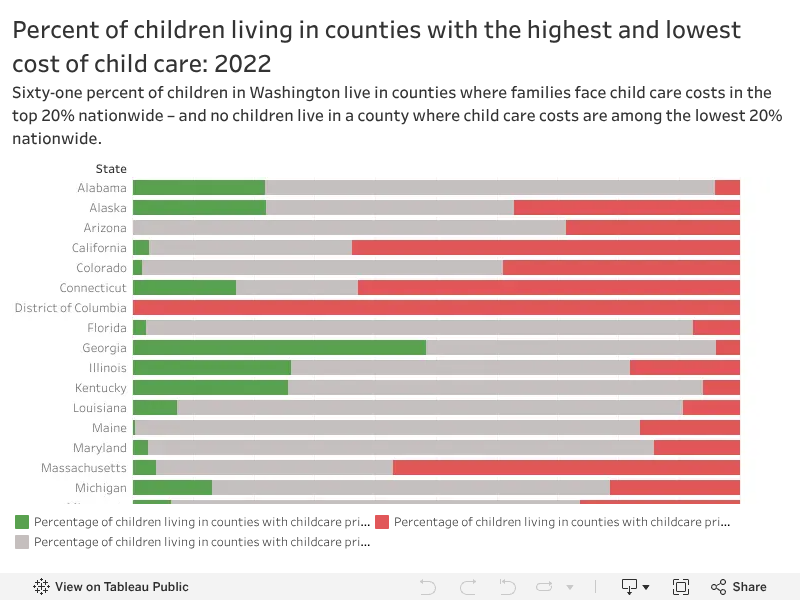
Affordable and reliable child care is crucial to a functioning economy – but the cost is out of reach for too many working families, and wages are far below what’s needed to attract and sustain a workforce. According to the U.S. Department of Labor:
U.S. families spend between 8.9% and 16.0% of their median income on full-day care for just one child, with annual prices ranging from $6,552 to $15,600 in 2022, the most recent year for which data are available. Even part-day care for school-aged children (e.g., before and after school care) comprises 8.1% to 9.4% of median family income: from $5,943 up to $9,211 for just one child. To put this into perspective, the median cost of a year’s worth of rent was $15,216 in 2022. [11]
From 2013 to 2023, the average monthly cost of care for Washington infants rose from 27% to 32% of median monthly wages; for toddlers, from 24% to 29%; and for preschoolers, from 21% to 25%. [13]
Wages for child care workers also significantly lag those of other workers. According to the Chicago Federal Reserve:
“The median wage paid to childcare workers is in the bottom 5% of all occupations and has grown less quickly than wages paid to workers in other service sector jobs in the post-pandemic period.” [14]

Self and Family Care
No one should have to choose between taking time off work for care – whether to recover from an illness, care for a loved one, or address legal or safety needs – and keeping their job or paycheck intact.
While little progress has been made at the federal level on paid sick/safe leave or paid family/medical leave policies, states and localities across the nation have taken matters into their own hands. Seattle, with EOI’s leadership, passed a local paid sick/safe time ordinance in 2012, and Washington enacted a similar measure in 2018, followed by a groundbreaking paid family and medical leave program in 2019. Other localities have followed suit – most recently in Alaska and Nebraska, where paid sick time laws took effect this year. [15]
Self and Family Care Policy Timeline: 1942-2025

Care Economy
Care workers are crucial to the well-being of individuals, families, and communities – from helping people heal and stay healthy, to watching and educating children, and caring for aging family members. The people in these roles make it possible for millions of other workers to participate in our economy.
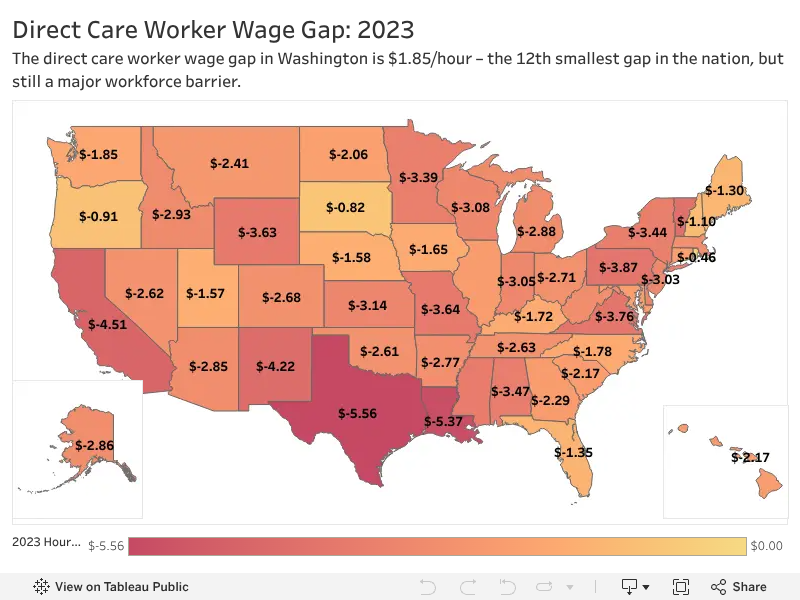
But despite the importance of direct care workers to our economy, entry-level median wages for those professions are significantly lower than those in similar occupations in other industries (such as retail, fast food, and others) [16]:
In all 50 states and the District of Columbia, the median wage for direct care workers is lower than the median wage for similar occupations in other industries. In 2023, the most recent year of data available, the hourly wage gap ranged from $0.46 in Rhode Island to up to $5.56 in Texas. The wage gap was at least $2.00 per hour in 39 states, and in 19 of those states, the wage gap was more than $3.00 per hour.
In Washington, the wage gap between direct care workers and the median wage of similar occupations in Washington stands at $1.85 per hour, placing it 12th among all states and the District of Columbia.
Thanks to recent improvements in the state’s minimum wage and wage transparency law – and (in Seattle) secure scheduling and wage theft protection – Washington is also one of 12 states where the wage gap has closed by $1.00 per hour or more since 2014.

Employment
For an economy to work for everyone, everyone who wants to work needs to be able to find employment – at least most of the time. While some unemployment is to be expected (for example, when workers voluntarily leave a job, or during economic downturns like a recession) long-term unemployment is an indicator that something is wrong with economic policies.
The unemployment rate produced by the Bureau of Labor Statistics (BLS), called “U-3”, represents the number of unemployed people actively seeking a job in the past four weeks. It gets the most media attention when it is published each month – but there’s another measure published by the BLS that is more reflective of how well the job market is (or isn’t) working for people.
The underemployment rate (called “U-6”) includes everyone in the U-3 rate, plus people who want to and are available for work (and have looked for a job sometime in the prior 12 months), as well as those who – not by choice – are working less than full-time.
Underemployment rates are consistently higher than unemployment generally. But Hispanic and Black workers tend to face higher underemployment than workers overall, while Asian/Pacific Islander and White workers tend to experience lower underemployment. Education creates even larger gaps: workers with an advanced degree typically face much lower underemployment than those without a high school diploma. Gender accounts for only a small difference.
In 2024, the underemployment rate for Hispanic workers was 6.2 percentage points higher, and for Black workers 2.9 percentage points higher, than overall underemployment in Washington. Workers with advanced degrees have an underemployment rate 5.0 percentage points lower, and those with less than a high school diploma have an underemployment rate 8.8 percentage points higher than overall underemployment. [17]


Higher Education
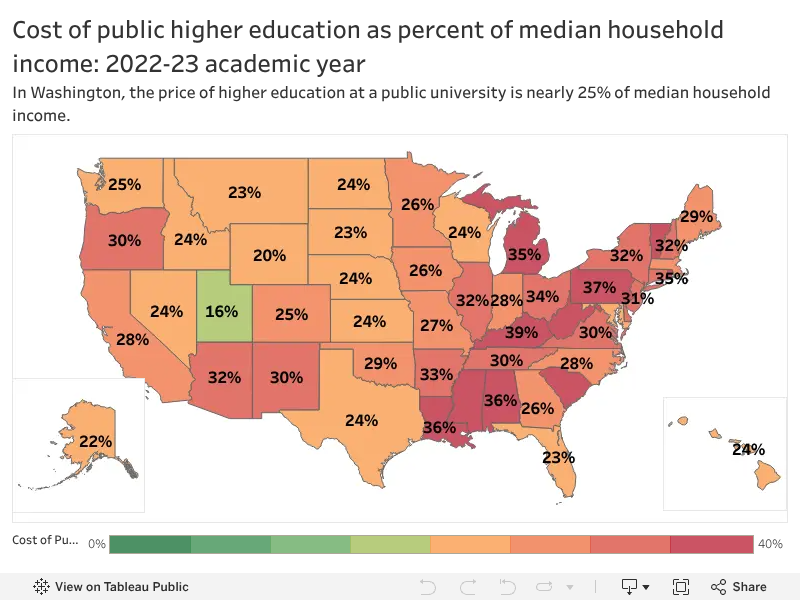
Higher education is a key contributor to family economic security and upward mobility. Public colleges and universities are critical resources for fulfilling the promise of economic opportunity. But the cost of higher education – and the education debt that saddles graduates – is too high a burden for too many students.
As a percentage of median household income, in 2022-23 (the latest year available) the total price of college (tuition, fees, room and board) for a full-time in-state public university student was lowest in Utah (16%) and highest in Mississippi (39%). In Washington, the price of higher education at a public university is nearly 25% of median household income.[18]
As of 2019-20 (the latest year available), average debt as a percentage of median household income for undergraduates of public colleges and universities was lowest in New Hampshire (21%, about $18,000) and highest in Mississippi (60%, about $40,000). Washington’s public university students graduated with an average $24,000 in debt in 2019-20, or about 31% of median household income. [19]

Childhood and Senior Poverty
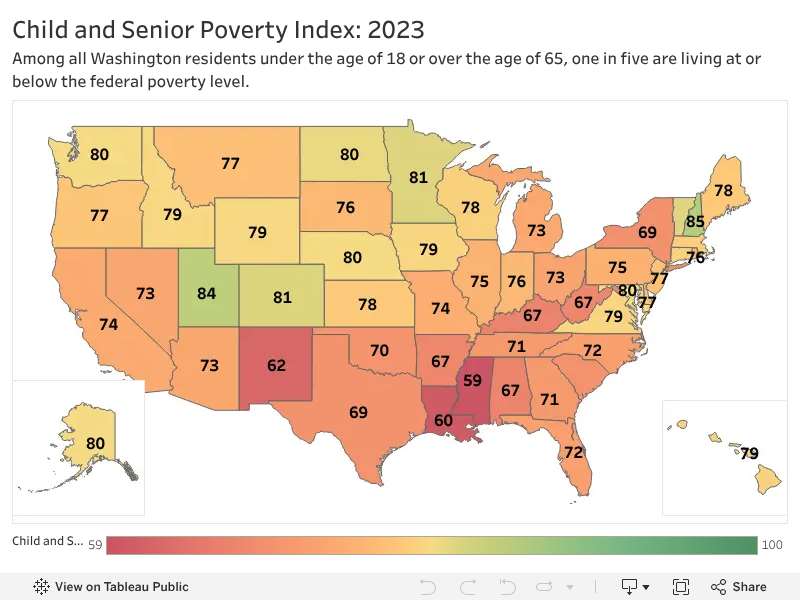
There are many measures of success (or failure) of social and economic policy, but few are more telling than the number of people – particularly the youngest and oldest in our communities – who are left behind economically. If child and senior poverty is low, a state’s economy is more likely to be doing right by its most vulnerable residents – and it’s more likely the economy is serving people better generally.
EOI’s Childhood and Senior Poverty Index (CSPI) is calculated using childhood and senior poverty rates. In a state with a score of 100, no child or senior would live in poverty. The good news is that since 2013, scores for all but five states have improved to some degree. Oregon (+7.2), Georgia (+7.0), and Arizona (+6.9) lead the way, while Louisiana (-0.4), Connecticut (-1.0), and Alaska (-2.0) have regressed most. In 2023, New Hampshire (84.8), Utah (83.9), and Colorado (81.1) led the nation with the highest CSPI score, while in New Mexico (62.3), Louisiana (60.2), and Mississippi (59.3), children and seniors fared worst.[20]
Washington’s CSPI of 79.6 places among the top 10 states overall, and since 2013, its score has improved by 5.2 points – among the top one-third of all states in terms of improvements. But that still means that among all residents under the age of 18 or over the age of 65, more than 1 in 5 are living in poverty.
It’s also important to note that the federal poverty level (FPL) understates the severity of the problem. The 2025 FPL for a family of four is just $32,150 in annual household income – and as a national standard, it doesn’t reflect the higher cost of living in states like Washington.

References
[1] The Good Jobs Index compares occupational wage data from the Bureau of Labor Statistics (https://www.bls.gov/oes/current/oessrcst.htm) with household budget data from the Economic Policy Institute: https://www.epi.org/resources/budget/. See Methodology for additional information.
[2] US Census Quarterly Workforce Indicators: https://qwiexplorer.ces.census.gov/
and Economic Policy Institute, State of Working America Data Library, “Hourly wage percentiles – Real hourly wage (2024$),” https://swx.epi.org/. See Methodology for additional information.
[3] Institute on Taxation and Economic Policy (ITEP), “Who Pays: A Distributional Analysis of the Tax Systems in All 50 States”, 5th Edition (published January 2015) and 7th Edition (published January 2024).
[4] See Methodology for additional information.
[5] Kaiser Family Foundation, “Employer-based Health Insurance Premiums and Deductibles”, https://www.kff.org/state-category/health-costs-budgets/employer-based-health-insurance-premiums/ and U.S. Bureau of Labor Statistics, “Chained Consumer Price Index for All Urban Consumers (C-CPI-U): U.S. city average”, https://data.bls.gov/timeseries/SUUR0000SA0.
[6] Kaiser Family Foundation, “Percentage of covered workers enrolled in an HDHP/HRA or an HSA-Qualified HDHP, 2006-2023), https://www.healthsystemtracker.org/indicator/access-affordability/percent-covered-workers-high-deductible-health-plans
[7] Office of the Insurance Commissioner, Washington State, Press Release, September 10, 2015, https://www.insurance.wa.gov/about-us/news/2025/average-21-rate-increase-approved-washingtons-2026-exchange-health-insurance-market
[8] Kaiser Family Foundation, September 2025, https://www.kff.org/affordable-care-act/aca-marketplace-premium-payments-would-more-than-double-on-average-next-year-if-enhanced-premium-tax-credits-expire/
[9] Washington Health Benefit Exchange, Fact Sheet, January 17, 2025 https://www.wahbexchange.org/content/dam/wahbe-assets/legislation/WAHBE-ePTC-fact-sheet-011725.pdf
[10] Kaiser Family Foundation, Estimated Medicaid Enrollment Loss in the House Reconciliation Bill By State, June 2025, Figure 3, https://www.kff.org/medicaid/allocating-cbos-estimates-of-federal-medicaid-spending-reductions-and-enrollment-loss-across-the-states/.
[11] U.S. Department of Labor, November 2024, “Childcare costs remain an almost prohibitive expense”, https://blog.dol.gov/2024/11/19/new-data-childcare-costs-remain-an-almost-prohibitive-expense
[12] National Database of Childcare Prices: State-Level Estimates and Affordability Rankings 2022, https://www.dol.gov/agencies/wb/topics/featured-childcare
[13] Kids Count Data Center, The Annie E. Casey Foundation, “Childcare provider rate in Washington”, https://datacenter.aecf.org/data/tables/5649-child-care-provider-rate and Economic Policy Institute, State of Working America Data Library, “Hourly wage, median – Median nominal hourly wage”, https://data.epi.org/wages/hourly_wage_median/cartogram/year/national/nominal_wage_median/state
[14] “The Labor Market for Childcare Workers”, Chicago Fed Insights, June 2024, https://www.chicagofed.org/publications/chicago-fed-insights/2024/childcare-labor-market.
[15] Family Values at Work, State and City Laws, https://familyvaluesatwork.org/your-rights/state-and-city-laws/. U.S. Department of Labor, Women’s Bureau, December 2024 Issue Brief, https://www.dol.gov/sites/dolgov/files/WB/StatePaidSickLeaveLaws.pdf.
[16] “Competitive Disadvantage: Direct Care Wages Are Lagging Behind – 2024 Update”, PHI, PHI-Competitive-Disadvantage-Factsheet-2024.pdf.
[17] Economic Policy Institute, State of Working America Data Library, “Underemployment – Underemployment rate” 2025, https://swx.epi.org/.
[18] U.S. Department of Education, National Center for Education Statistics, Integrated Postsecondary Education Data System (IPEDS), Institutional Characteristics component final data (2002-03 – 2022-23) and provisional data (2023-24) and U.S. Census Bureau, Historical Income Tables: Households, Table H-8A: Median Income of Households by State Using Two-Year Moving Averages (Current Population Survey, 1985 to 2024 Annual Social and Economic Supplements).
[19] The Project on Student Debt, Institute for College Access and Success, https://ticas.org/interactive-map/, and U.S. Census Bureau, Historical Income Tables: Households, Table H-8A: Median Income of Households by State Using Two-Year Moving Averages (Current Population Survey, 1985 to 2024 Annual Social and Economic Supplements).
[20] Poverty Status, American Community Survey 2023 (5-Year Estimates) and American Community Survey 2013 (5-Year Estimates), U.S. Census Bureau.
Methodology
Good Jobs: If all people working full time in any one occupation were divided into four equally sized groups, then the 25th percentile wage represents the average wage for the bottom 25% of all positions in that occupation; the 50th percentile (median) is the average wage for half of all positions; and the 75th percentile is the average wage for the bottom three-quarters of all positions. The Good Jobs index is calculated by:
1) Summing: 1) “Occupations Above Budget” (the number of occupations that pay enough to support a budget) for the following household configurations: 1 adult, 1 adult/1 child, 1 adult/2 children, at the 25th, 50th, and 75th percentile wage, respectively, for each state’s metropolitan areas and 2) “Total Occupations” (the total number of occupations in each state’s metropolitan areas for each of the same household configurations). For households with two adults, each adult is assumed to contribute 50% of the household’s budget.
2) Totaling “Occupations Above Budget” and “Total Occupations” at the 25th, 50th (median), and 75th percentiles for all metropolitan areas in each state.
3) Dividing total “Occupations Above Budget” by “Total Occupations” at the 25th, 50th (median), and 75th percentiles, yielding the percentage of occupations paying wages sufficient to support a family budget at each wage percentile for each state.
5) Weighting the resulting percentages of occupations paying sufficient wages accordingly: 25th percentile at 45%, the 50th percentile (median) at 30%, and the 75th percentile at 25%, then summing the results to create the state’s index score.
Wage Equity: Quarterly wages (by race/ethnicity and gender) for Q3/Q4 2013 and Q1/Q2 2014 were summed, adjusted to 2024 dollars using the Extended Chained Consumer Price Index for Urban Consumers (C-CPI-U), then compared to Quarterly wages (by race/ethnicity and gender) for Q3/Q4 2023 and Q1/Q2 2024. Average yearly wages at the 20th and 80th percentile were determined for 2014 (adjusted for inflation using C-CPI-U) and compared to the same percentiles in 2024.
Tax Equity: The Tax Equity Index (TEI) is calculated by converting data for each state as of 2024 (provided by Institute on Taxation and Economic Policy) to an index of 0 to 100, with the most regressive state score equal to 0 (highly regressive) and the inverse of that score equal to 100 (highly progressive). This means the TEI does not rank states – so it’s possible for states to have the same score – and it sets the top (progressive) end of the scale as far from the middle as the bottom (regressive) is, creating a more accurate spectrum of possible state tax structures.
- Leave a Reply
More To Read
State of Working Washington
August 10, 2021
New State Programs May Ease a Short-Term Evictions Crisis, but Steep Rent Hikes Spell Trouble
State and local lawmakers must fashion new policies to reshape our housing market
State of Working Washington
November 20, 2020
We Can Invest in Us
Progressive Revenue to Advance Racial Equity